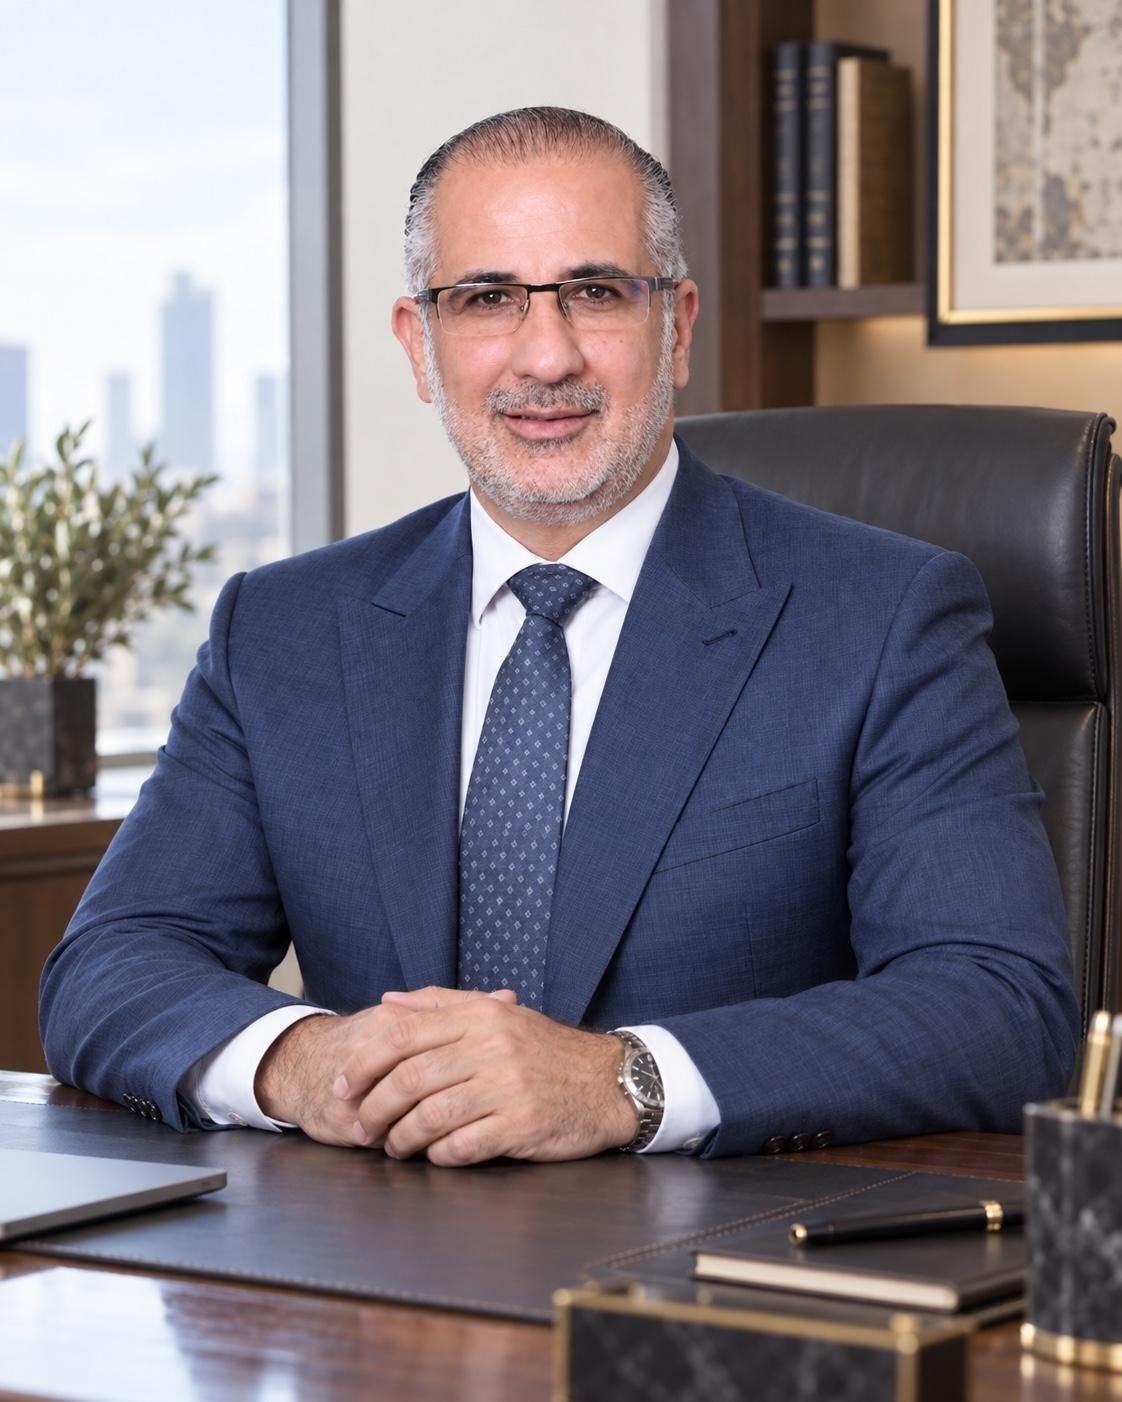
THE FOUNDER

Rami Ziad Khayyat

Senior banking executive and advisor with more than three decades across conventional and Islamic banking, corporate credit, investment and consulting, with experience spanning Jordan, Saudi Arabia, the UAE and Iraq.

Rami Ziad Khayyat seated at his office desk

Leadership & professional affiliations

Founding the Jordan Chapter

Arab Leadership Intelligence Council (ALIC)

Rami took part in founding the Jordan Chapter of the Arab Leadership Intelligence Council in Amman and was recognized as a Founding Leadership Ambassador. His contributions focused on investment, business expansion, capital readiness and regional collaboration.

Council announcement ↗

Member

Jordanian Businessmen Association

Rami is a member of the Jordanian Businessmen Association and the Federation of Arab Businessmen.

THE RECORD

Experience in building and leading.

Before founding KCH in 2024, Rami held senior responsibilities in corporate banking and executive management, including Deputy CEO, Head of Corporate Banking and Acting CEO. His work included establishing a corporate banking department from the ground up, developing its business, building long-term business relationships.

30+

YEARS — Banking, credit and investment across conventional and Islamic institutions.

$1.6B

PRIOR CAREER — Working with his team, he helped grow a corporate banking business from near zero to more than USD 1.6 billion over approximately 14 years, maintaining strong asset quality. This experience predates KCH.

CEO

ACTING APPOINTMENT — Appointed Acting CEO by the Board of Directors, with delegated responsibilities.

4

MARKETS — Professional experience across Jordan, Saudi Arabia, the UAE and Iraq.

EXECUTIVE EXPERIENCE

Responsibilities in practice.

Corporate Banking DepartmentEstablishing a corporate banking department from the ground up and overseeing the development of its business.
Board responsibilitiesChairman, Deputy Chairman and Board Member across investment, financial, industrial and real-estate companies.
Sharing knowledgePart-time lecturer and banking trainer in credit, management and financial analysis.
PROFESSIONAL CONTRIBUTIONS

Professional contributions.

Industry and export supportRecognition for membership of the High Selection Committee in the Export Promotion and Industry Support Program.
International conferences & dialogueOver the years, Rami has participated in conferences, seminars, workshops and panel discussions in regional and international settings, contributing to conversations on banking, investment and economic development.
Articles and published perspectivesRami has contributed to newspapers, specialist magazines and digital publications in Jordan, the Arab region and internationally over the years. These selected articles explore finance, investment, technology and economic development.
Professional memberships and engagementMember of the Jordanian Businessmen Association and the Federation of Arab Businessmen; teaching and contributions to economic and financial discussion.
Arab Leadership Intelligence Council (ALIC)Rami took part in founding the Jordan Chapter of the Arab Leadership Intelligence Council in Amman and was recognized as a Founding Leadership Ambassador. His contributions focused on investment, business expansion, capital readiness and regional collaboration.
Excellence in Business Leadership · The BIZZ 2017Personal recognition awarded to Rami Al Khayat by the World Confederation of Businesses (WORLDCOB), Houston, November 2017.
Academic and professional contributions & knowledge sharingContributions to teaching, training, seminars and economic and banking discussions, sharing practical experience with academics, professionals and students.

Selected conferences & engagements

Examples from a broader record of professional participation in regional and international forums.

Impact Jordan · AmmanPanel participation on impact initiatives and the role of Islamic finance.
Middle East Institute · WashingtonParticipation in a discussion on Syria’s economic outlook, financial reforms and investment prospects.
Jordan Business Forum · AmmanFeatured speaker at the 2025 forum.
Jordanian–Syrian Cooperation & Investment Forum · DamascusParticipation in discussions on investment opportunities and economic cooperation.
Fintech Summit 2026 · AmmanParticipation and exchanges with business and technology leaders on financial technology and digital transformation.
First Arab World Congress for Creativity · BaghdadInvited participation in the congress and discussions with Iraqi business leaders, investors and officials on potential cooperation and joint initiatives.
KCH business engagement · East AfricaVisits following official government invitations to explore banking, investment, fintech, trade and business development opportunities with public- and private-sector counterparts.
Jordan–China business dialogue · AmmanMeetings with a business delegation from Binzhou, China, to discuss economic, investment and trade cooperation.

Selected articles & perspectives.

Rami has contributed to newspapers, specialist magazines and digital publications in Jordan, the Arab region and internationally over the years. These selected articles explore finance, investment, technology and economic development.

Islamic Finance news

Does Islamic finance fulfill its economic promises?

Drawing on Jordan’s experience, Rami asks whether Islamic finance has delivered its intended economic impact. He argues that success should be judged by support for production, entrepreneurship and access to finance, alongside sound governance and a supportive institutional environment. His analysis acknowledges the sector’s contribution to financial stability while examining the gap between principles and practice.

Read the article · Original English

Does Islamic finance fulfill its economic promises?

Since its inception, Islamic finance has been built upon a clear economic philosophy aimed at linking financial activity to the real economy. It emphasizes asset-backed transactions, fairness in risk sharing and balanced relationships among all parties involved. The objective was never merely to provide a Shariah compliant alternative to conventional finance, but rather to establish a more stable, equitable and sustainable financial model capable of addressing structural weaknesses created by excessive reliance on debt. RAMI KHAYYAT investigates.

As the industry has expanded regionally and globally, a fundamental question has become increasingly relevant: has Islamic finance genuinely fulfilled its economic promises, or has it largely focused on achieving formal Shariah compliance without delivering the intended developmental impact?

From a Jordanian perspective, this question carries particular importance. Jordan is a resource-constrained economy that depends heavily on the private sector, with SMEs representing the backbone of economic activity and employment. In such an environment, access to finance is not merely supportive but essential for economic stability, business continuity and sustainable growth.

In theory, the principles of Islamic finance align closely with the needs of the Jordanian economy. Asset-backed financing, avoidance of excessive leverage, transparency and equitable risk distribution are all elements that can support balanced and long-term development. However, the gap between theory and practice remains the key factor in assessing the true economic impact of this model.

In practical terms, Islamic finance in Jordan has contributed positively to several key sectors, particularly trade, real estate and productive activities linked to real assets. Many companies have benefited from financing structures connected to genuine commercial transactions, enabling them to manage working capital more efficiently and finance expansion in a more disciplined manner compared with purely cash-based lending.

However, the success of Islamic finance cannot be measured solely by the availability of products. What ultimately matters is their effect on the broader economy. In practice, many Islamic financing structures generate economic outcomes similar to those of conventional finance. The distinction often lies more in legal documentation and Shariah compliant structuring than in economic substance. This highlights a central challenge: while compliance has largely been achieved, the developmental impact has not always reached its expected level.

This outcome is driven by practical constraints. In a relatively small market such as Jordan’s, Islamic financial institutions face ongoing pressures related to pricing, liquidity, credit risk and competition. These pressures often encourage institutions to favor low-risk and predictable financing structures over profit-and-loss sharing models such as Mudarabah and Musharakah, which represent the philosophical core of Islamic finance. Despite their conceptual importance, these structures remain limited in practice due to higher operational risks and the absence of a sufficiently supportive environment. Liquidity management also plays a critical role. The limited availability and relatively higher cost of Shariah compliant instruments reduce flexibility and constrain innovation. As a result, institutional stability frequently takes precedence over experimentation and long-term developmental considerations.

Although SMEs are theoretically the primary beneficiaries of Islamic finance, they continue to face challenges related to governance, transparency and the quality of financial reporting. Consequently, financing — whether Islamic or conventional — often remains concentrated among larger and well-established companies, rather than being directed toward smaller and emerging enterprises that are widely recognized as the true drivers of economic development.

At this stage, an essential reality becomes evident: Islamic finance cannot fulfill its economic promises in isolation. Its effectiveness depends on operating within a coordinated and supportive economic ecosystem. Meaningful developmental impact requires alignment among regulatory authorities, legislators, supervisory institutions and the legal system, in addition to a business environment capable of accommodating the specific characteristics of Islamic financial models.

Islamic finance requires legislation that supports partnership-based structures, legal frameworks that enable efficient dispute resolution, supervisory approaches that understand the nature of Islamic risk and economic policies that encourage productive investment. Without such integration, the sector remains constrained, regardless of the strength or professionalism of the institutions operating within it.

Governance represents another cornerstone in realizing the economic promise of Islamic finance. The model does not focus solely on the formal validity of contracts; it assumes ethical conduct, clarity of rights and balanced obligations among all parties. When governance becomes merely procedural, Islamic finance loses a significant portion of both its ethical foundation and its economic effectiveness.

Despite the challenges, it would be inaccurate to conclude that Islamic finance has failed in Jordan. On the contrary, the sector has achieved steady growth and secured an increasingly meaningful position within the financial system. It has contributed positively to financial stability and has helped limit excessive risk, even if its broader developmental role remains incomplete.

The next phase should therefore emphasize qualitative advancement rather than quantitative expansion. This involves moving from form to substance, reducing reliance on replicating conventional instruments and strengthening the connection between finance and real economic production, entrepreneurship and value creation.

In conclusion, the Jordanian experience illustrates a crucial insight: Islamic finance does not automatically fulfill its economic promises simply by existing. Its success depends on the depth of its application, the sincerity with which its principles are implemented and the level of integration with the surrounding economic framework. When approached as a comprehensive economic model rather than a legal structure alone, Islamic finance can move closer to the vision upon which it was originally founded.
Published pagesPage 1Page 2

Islamic Finance news5 February 2025 · pp. 25–26

Islamic finance in Jordan: Reality and challenges

An assessment of the sector’s development, access to finance for SMEs, and the potential of sukuk and digital financial services.

Read the editorial summary

The article traces the development of Islamic finance in Jordan and considers how its financing structures serve the real economy. It examines the opportunities offered by sukuk, renewable-energy financing, digital banking and financial technology.

Alongside these opportunities, Rami discusses practical barriers: limited public understanding of some financing instruments, regulatory constraints, a concentrated market and the need for products better suited to smaller businesses. He calls for stronger governance, clearer rules and a broader range of financing options.

مجتمع الأعمالBusiness Community magazine · pp. 40–41

Legal frameworks and challenges facing fintech in Jordan

How regulation, customer protection, data privacy and financial-crime controls can support responsible fintech development.

Read the editorial summary

The article examines how Jordan’s legal and regulatory framework can keep pace with digital finance. It identifies customer protection, payment security and the privacy of financial data as central to public trust.

Rami argues for coordination among regulators, banks and technology companies, supported by practical training and effective controls against money laundering and terrorist financing. The objective is to encourage innovation while protecting consumers and maintaining financial stability.

مجلة جمعية رجال الأعمال الأردنيينJordanian Businessmen Association magazine · December 2021 · p. 25

The role of Islamic banks in stimulating investment in Jordan

An examination of productive investment, long-term financing, leasing and the role of Islamic sukuk in Jordan’s development.

Read the editorial summary

Rami connects Islamic finance to productive activity, employment and economic development. He reviews the roles of Murabahah, leasing and other structures, while considering the practical obstacles to financing long-term projects.

The article discusses transaction costs and the legal treatment of leasing, and considers how Islamic sukuk could help fund development and infrastructure. It argues that an enabling legislative and investment environment is essential to putting available liquidity to productive use.

Islamic Finance news3 February 2021 · pp. 29–30

The pandemic’s effects on Islamic banks in Jordan

A contemporary assessment of the pandemic’s impact on Islamic banking, credit, profitability and the transition to digital services.

Read the editorial summary

Writing during the pandemic, Rami examines the resilience of Jordan’s Islamic banks alongside pressures on profitability, financing activity and repayment. He discusses rescheduling measures, the limits of some financing structures and the importance of prudent risk assessment.

The article also explores the accelerated adoption of digital banking and financial technology. Its forward-looking themes include broader financing tools, social finance, responsible investment and new sources of income while preserving the sector’s developmental purpose.

START WITH THE SITUATION

Put three decades of institutional judgement on your side of the table.